
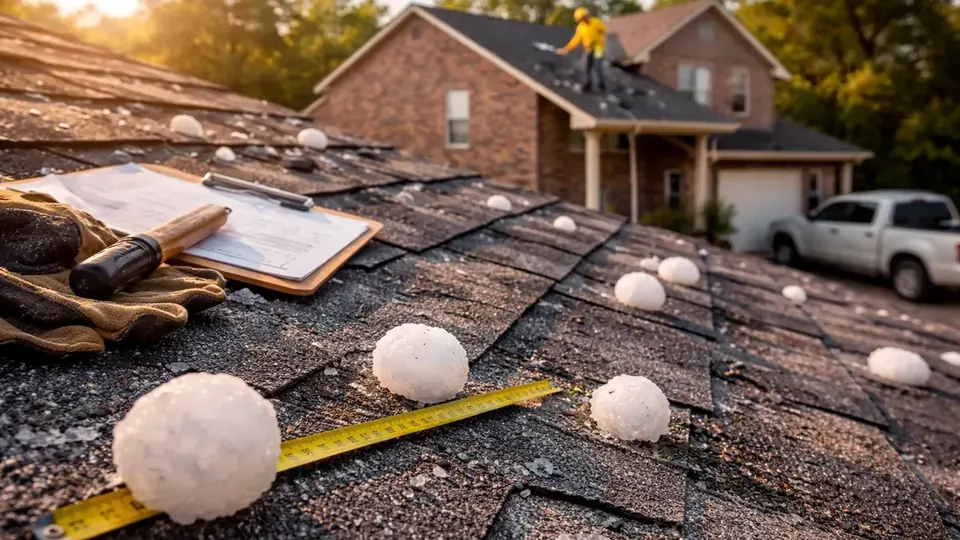
San Antonio hail damage claims are among the most common property insurance claims in Bexar County, and the weather record explains why. The NOAA Storm Events Database lists 618 hail reports in the county since 1957, and 203 of them were golf-ball size (1.75 inches) or larger. Reports cluster from March through May, with April the busiest month by a wide margin. The largest stone on record, 5.5 inches, fell near Sayers and the China Grove area on the east side on May 3, 2021 (NCEI event record).
Hail damage is often harder to see than it sounds. Bruised shingles, cracked tiles, and dented metal can be invisible from the yard, and the full scope may show up only during a close roof inspection. This page explains what a hail claim usually involves, where disputes start, and how a public adjuster in San Antonio may help. For the numbers behind hail season, read San Antonio hail season storm data.
Major Hailstorms in Bexar County
Several storms show how much damage hail can do here in a single afternoon:
- April 12, 2016. Giant hail crossed northwest and north San Antonio. NOAA recorded 4.5-inch hail near Tezel Road and Bandera Road, which at the time tied the largest hailstone ever reported in Bexar County (NCEI), 4-inch hail near Bandera Road and Loop 1604, 3.5-inch hail in Leon Valley, and 3-inch hail in Olmos Park. It is widely reported as one of the costliest hailstorms in Texas history.
- May 6, 2001. NOAA describes it as one of the most devastating hail-and-wind storms in Bexar County history, with hail up to 4 inches and winds over 60 mph that destroyed roofs of hundreds of homes (NCEI).
- May 3, 2021. Along with the 5.5-inch stone near Sayers, 4.5-inch hail was reported near I-410 and Paula Drive in eastern San Antonio.
- May 26, 2025. Hail up to 3 inches was reported in Helotes (NCEI).
Because Bexar County can see dozens of hail reports in an active year, insurers often ask which storm caused the damage. Dating the loss correctly is one of the first things we work on.
What Hail Damages on San Antonio Properties
Hail is a named peril on most homeowners and commercial property policies, subject to deductibles, exclusions, and endorsements. Claims here frequently involve:
- Roofs. Composition shingles (granule loss, bruising, fractured mats), standing-seam metal common toward the Hill Country edge, tile, and flat or low-slope commercial membranes. See our roof damage insurance claims page.
- Windows and skylights. Broken glass, split frames, torn screens.
- Exterior walls. Spatter and chips on stucco, cracked siding, damaged trim and fascia. Limestone and brick veneer usually hold up, but mortar, sealants, and trim around them may not.
- Soft metals and equipment. Gutters, downspouts, roof vents, and condenser coil fins on AC units.
- Other structures. Fences, carports, sheds, pergolas, and metal outbuildings.
- Interior water damage from broken windows or punctured roofing, which is usually handled as part of the same hail claim.
Documentation That Supports a Hail Claim
Good documentation ties the damage to a storm date and shows the full scope of repairs. Our claim documentation checklist covers this in more detail.
| Document | Why it matters |
|---|---|
| Date-stamped photos and video | Shows hail size, roof condition, and damage before tarping or repairs. |
| Weather records (NOAA, NWS) | Helps confirm hail fell at or near the property on the date of loss. |
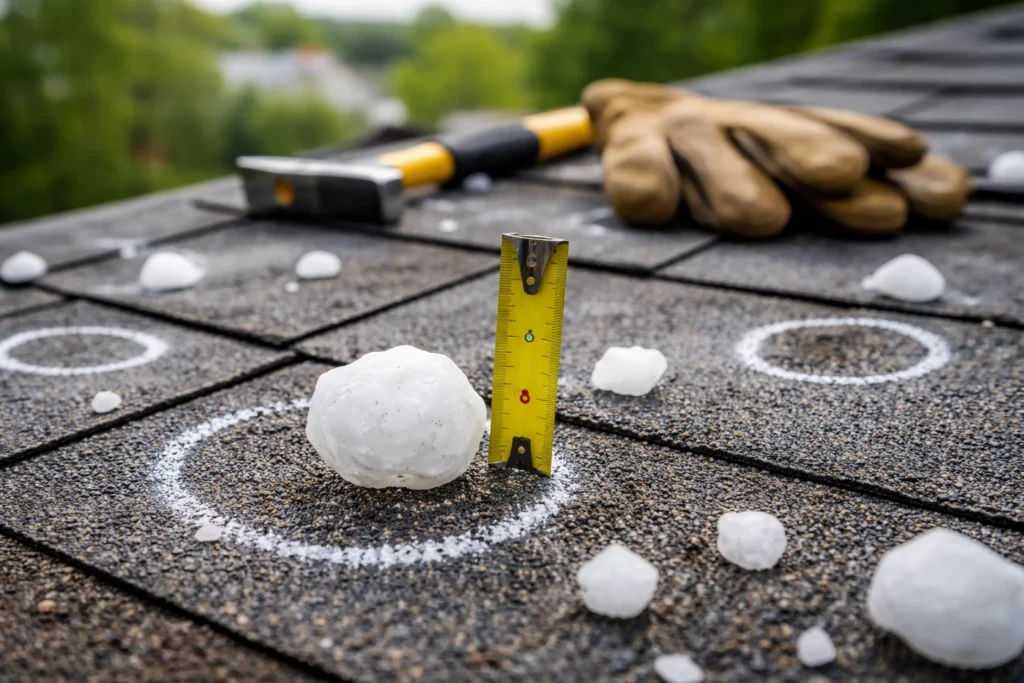
| Roof inspection with test squares | Records hits per square, mat fractures, and functional damage by slope. |
| Itemized repair estimate | Line-item scope (often in Xactimate) for roofing, gutters, windows, and interior work. |
| Policy and declarations page | Confirms deductibles, roof payment schedules, and cosmetic damage endorsements. |
| Receipts for emergency repairs | Supports reimbursement for tarping and mitigation. |
Common Insurer Arguments on Hail Claims
- “Wear and tear, not hail.” The insurer attributes granule loss or cracking to age, blistering, or manufacturing defects. South Texas heat ages shingles, which gives this argument traction.
- “Prior storm.” The carrier says the damage came from an earlier, unreported storm or one before the policy period.
- “Cosmetic only.” Dents on metal roofing or soft metals are labeled cosmetic under an exclusion endorsement.
- Repair instead of replace. The estimate allows spot repairs even when brittle or discontinued materials cannot be repaired or matched.
- Missing line items. Drip edge, starter course, ridge, flashing, permits, and code-required items are left out. Our insurance estimate review looks for these gaps.
Settlement Factors to Understand
- Wind/hail deductibles. Often a percentage of the dwelling limit. Check your declarations page.
- ACV vs. replacement cost. Under replacement cost coverage, insurers typically pay actual cash value first and release recoverable depreciation after repairs are finished. Some roof coverage is ACV-only or follows a payment schedule. See replacement cost vs. actual cash value in Texas.
- Code upgrades. Re-roofing inside city limits generally requires a permit through the City of San Antonio Development Services Department. Code-required work is paid only if your policy includes ordinance or law coverage, up to its limit. See local building codes.
Personal property, other structures, and additional living expenses each have their own limits, so check every coverage section, not only the dwelling limit.
How San Antonio Public Adjuster Can Help
San Antonio Public Adjuster is a public adjusting service of Rise Public Adjusting LLC, licensed by the Texas Department of Insurance. A licensed public adjuster represents the policyholder, not the insurer. On a hail claim, that may include inspecting the roof and exterior, reviewing the policy, preparing a detailed estimate, gathering weather data, and communicating with the insurer's adjuster. If the claim was already paid low, we can review it for an insurance claim supplement or discuss whether appraisal fits a dispute over the amount of loss. We cannot guarantee a result. Fees are disclosed in a written contract before any work begins; Texas law caps public adjuster compensation at 10% of the insurance settlement.
Your Responsibilities After a Hailstorm
- Give prompt notice to your insurer.
- Protect the property from further damage (tarp openings, board windows) and keep receipts.
- Photograph damage before repairs and keep samples of damaged materials when practical.
- Submit a proof of loss if requested, within the time your policy requires.
- Cooperate with inspections and reasonable document requests.
Many policies also set a contractual deadline to file suit. For legal questions about deadlines or a dispute, consult a Texas attorney.
Frequently Asked Questions
How long do I have to report hail damage in San Antonio?
Most policies require “prompt” notice, and some set a specific window for reporting wind and hail losses. Check the conditions section of your policy and report as soon as you discover damage. Waiting makes it harder to tie the damage to a specific storm date, especially in a busy hail season.
How do I prove which storm caused the hail damage?
Dated photos, NOAA Storm Events records, National Weather Service reports, and the condition of soft metals such as vents, gutters, and AC fins can help connect damage to a date. Our storm lookup tool and Bexar County storm history page are good starting points.
Is my wind and hail deductible different from my regular deductible?
Often, yes. Many Texas policies use a separate wind/hail deductible written as a percentage of your dwelling (Coverage A) limit. Your declarations page shows the amount. Bexar County is not in the TWIA area, so wind and hail coverage usually comes from your regular insurer.
What is a cosmetic damage exclusion?
Some policies, especially for metal roofs, exclude dents that do not affect how the roof sheds water. Whether a dent is cosmetic or functional is a common dispute on standing-seam and corrugated metal roofs around San Antonio. Read your endorsements before the inspection.
Will the insurer replace my whole roof after hail?
It depends on how much of the roof is damaged, whether the materials can be repaired or matched, and your policy terms. Some losses support full replacement; others are scoped as repairs. A detailed inspection and line-item estimate help show which applies.
Can a public adjuster guarantee a larger hail settlement?
No. A public adjuster can help document the loss, review the insurer’s estimate, and present the claim, but no one can guarantee an outcome. Results depend on your policy and the facts of the loss.